Founder economics: fees, performance fee and “skin in the game”
“How does the founder make money from the fund? In two ways: a small fixed fee for keeping the fund running, and a large share of the upside when the fund makes money. The latter is the real driver.”
Key points
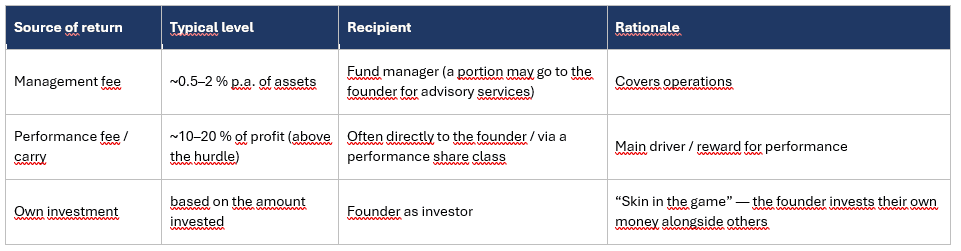
The founder typically earns in three layers:
Performance fee — how it is structured in practice
- Hurdle rate (preferred return): investors first receive a preferred return (e.g. up to 6–8 % p.a.). Only above that is the upside shared.
- Sharing above the hurdle: e.g. everything above 6 % is split 50:50, or the founder receives 20 % of the profit above the threshold. The variants are flexible and described in the fund statute.
- Alternatively, a High-water mark: the founder receives performance only on a new high in value — the same appreciation is not charged twice after a decline and recovery.
How performance technically “flows” to the founder
- Founder performance share class (common and clean): profit above the hurdle is allocated to a separate share class held by the founder — standard and tax-efficient.
- Fee at fund level: performance fee is an expense of the fund and is paid to the fund manager/founder.
- Advisory fee: the founder’s company invoices the fund for investment advisory services (fixed + performance component).
“Skin in the game” — why the founder invests their own money
- Investors want to see that the founder takes risk alongside them. Co-investment is the strongest credibility signal.
- At the same time, it is a legitimate source of return — the founder also earns as an investor, not only from fees.